
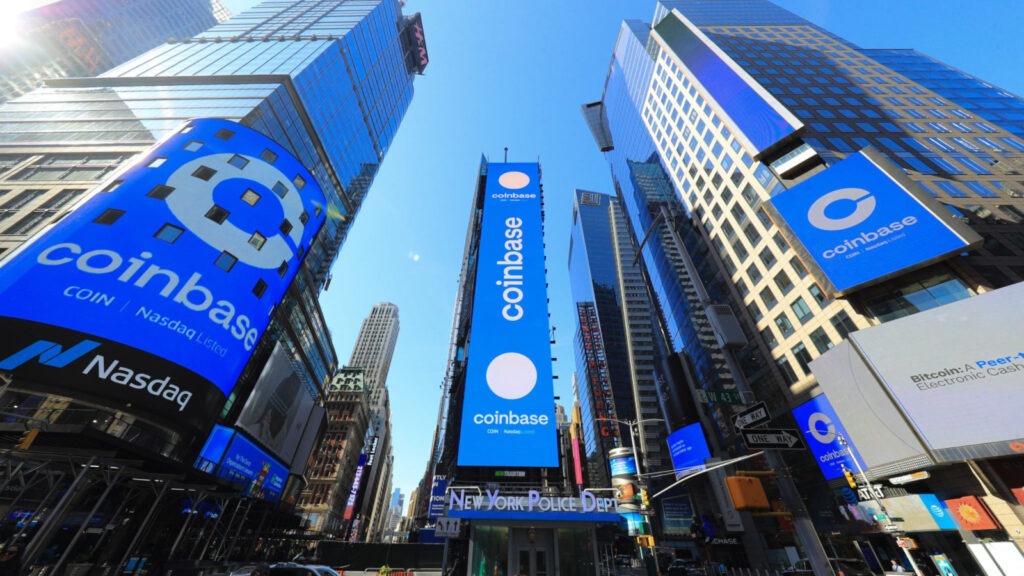
Bernstein analysts Gautam Chhugani and his team published a note on Monday arguing that the 60% collapse in cryptocurrency-adjacent stocks from their all-time highs represents a “rare chance to buy the dip at a ‘big’ discount” — language that runs directly against the prevailing mood of Extreme Fear gripping the market.
The note maintained Outperform ratings on Coinbase, Robinhood, and Figure Technology Solutions while lowering price targets on all three to reflect expectations of weak first-quarter results when those companies report earnings in the coming weeks.
Bernstein’s argument rests on a structural view rather than a near-term price call: the analysts believe crypto equities are approaching a floor “into weak Q1 earnings” and that the Iran-war-driven macro pressure that has hammered the sector is temporary rather than structural.
Coinbase’s earnings per share are projected to grow 23% in 2026, driven by what Bernstein describes as a coming “stablecoin boom” and the rollout of new products that reduce revenue dependence on spot trading fees — the most volatile element of the exchange’s income.
The Fear and Greed Index for crypto sits at 8, in Extreme Fear territory, a reading last seen during the August 2025 flash crash that in retrospect marked a local price bottom. On-chain analysts note that nearly half of all circulating Bitcoin is currently underwater, with long-term holders selling at a loss — historically a signal that a capitulation phase is reaching its final stages rather than beginning.
Bitcoin itself is holding just above $67,000, attempting a modest rebound after testing the $65,900 support level, with the recovery capped by the $296 million in net ETF outflows recorded last week — the first net outflow week after four consecutive weeks of inflows.
Whether the Bernstein call ages well depends almost entirely on the Iran war duration. A ceasefire signal would likely trigger a sharp snap-back across risk assets including crypto. A continuation into May would test both the $65,000 support and Bernstein’s confidence in the sector’s structural resilience.
Bitcoin’s week has been a microcosm of the broader market — sharp falls when the Iran conflict escalated, an equally sharp recovery when ceasefire signals emerged, and then a fragile, news-dependent consolidation that left technical analysts deeply cautious. On Monday, Bitcoin briefly dipped below $68,000 as oil prices spiked above $112 per barrel and a broad risk-off move swept digital assets. By Wednesday, with Trump’s Truth Social post generating peace talk optimism, it had recovered to trade above $71,000.
At 9am Eastern on Wednesday, Bitcoin was priced at approximately $71,299, up modestly from Tuesday’s levels and roughly $16,100 lower than at the same point a year ago. Iran’s rejection of the US ceasefire proposal — which among other terms included a demand for control of the Strait of Hormuz — injected fresh uncertainty, but the market absorbed it with more composure than it had shown earlier in the week.
What the price movement this week has confirmed is something analysts have been arguing for months: Bitcoin has become deeply entangled with global macro sentiment rather than behaving as an uncorrelated asset. The phrase “digital gold” feels increasingly hollow when BTC falls in lockstep with equities during risk-off episodes and rises with them when geopolitical tension eases. Gold, in contrast, has absorbed $16 billion in ETF inflows year to date while Bitcoin ETFs have seen $4.5 billion in outflows over the same period.
On the institutional side, Michael Saylor’s Strategy has accumulated roughly 90,000 BTC in Q1 2026 alone, including a $76.6 million purchase of 1,031 coins, bringing total holdings to over 762,000 BTC. That accumulation acts as a structural demand floor during selloffs, reducing the probability of a severe crash even as retail sentiment remains cautious. The Fear and Greed Index sits at 25/100, firmly in fear territory. Technical indicators are mostly bearish, with Bitcoin’s 200-day EMA sitting at around $86,916 — a long way above current prices. The five-day pause in US strikes on Iran expires around March 28, and that date now functions as the most immediate catalyst for Bitcoin’s next significant directional move.
Monday was a sharp reminder of how directly Bitcoin now responds to geopolitical developments rather than purely crypto-native signals. When Trump posted on Truth Social that US strikes on Iran’s infrastructure would be paused for five days following “very good and productive” talks, Bitcoin jumped approximately 5% and broke back above $71,000.
The move came after a weekend that had seen Bitcoin drop below $67,600, with $336 million in total crypto liquidations over 24 hours and roughly $100 million in Bitcoin long positions wiped out as oil spiked and risk-off sentiment dominated.
Galaxy Digital, Coinbase, and IREN each gained around 2% in pre-market trading. Strategy — formerly MicroStrategy and the largest corporate Bitcoin holder — rose more than 3%.
The relief proved short-lived. Iran’s Fars news agency denied any direct or indirect talks with the US, which contradicted the White House narrative and caused markets to give back a portion of the gains.
By Tuesday morning, oil had jumped 4% on reports that Saudi Arabia and the UAE were moving toward joining the coalition against Iran. Bitcoin consolidated rather than extended.
Options markets reflected the unease. Put options on Deribit continued to trade at an 8-to-10 volatility point premium to calls through the June-end expiry — essentially unchanged from before Monday’s announcement. Traders are treating the geopolitical news with scepticism rather than pricing in a resolution.
The Fear and Greed Index fell to 8 at its low point over the weekend — deep inside “extreme fear” territory — before recovering somewhat on Monday’s news to settle in the mid-30s by Tuesday.
One structural positive amid the turbulence: spot Bitcoin ETFs have now recorded net inflows for four consecutive weeks. Last week alone, net inflows reached $95.18 million, indicating institutional capital is maintaining long-term allocations regardless of short-term volatility.
Bitcoin’s correlation with gold during this period has been telling. Gold has attracted strategic central bank buying even under geopolitical stress. Bitcoin has traded more like an equity — correlating closely with the S&P 500 rather than functioning as a haven.
The divergence does not invalidate the long-term institutional thesis. It does suggest that Bitcoin’s “digital gold” narrative requires a certain baseline of macro stability to sustain itself, and the current environment has not provided that.
If the Strait of Hormuz situation de-escalates meaningfully, the geopolitical headwind on crypto removes itself and the structural institutional demand story reasserts. Until then, the market is navigating a macro environment it cannot control.
When spot Ethereum ETFs received SEC approval in 2024, they came with a significant constraint attached: the funds were explicitly prohibited from staking the ETH they held. Regulators at the time were concerned that staking arrangements might constitute unregistered securities offerings, a legal question that Gary Gensler’s SEC had no appetite to resolve in favor of asset managers. That prohibition has now been reversed, and the product BlackRock launched on Nasdaq on March 12 is the clearest possible demonstration of how much the regulatory landscape has shifted.
The iShares Staked Ethereum Trust, trading under the ticker ETHB, is BlackRock’s third crypto ETF and its first designed to generate yield for shareholders rather than simply track price. Under normal market conditions, between 70% and 95% of the fund’s ETH holdings are staked through Coinbase Prime, with investors receiving approximately 82% of gross staking rewards, currently running at roughly 3.1% annually, distributed monthly. BlackRock and Coinbase split the remaining 18% as a staking fee, with downstream validators including Figment, Galaxy Digital, and Attestant handling the actual network participation.
Two regulatory developments made this structure legally viable. The first was the GENIUS Act, a federal stablecoin framework passed in July 2025 that clarified the legal runway for yield-generating crypto products more broadly. The second was the change in SEC leadership, with Paul Atkins replacing Gary Gensler as chair. Atkins’ SEC approved ETHB’s structure without objection after roughly three months of review, a timeline made possible by new generic listing standards that compressed the process from as long as 240 days to as little as 75.
ETHB attracted $155 million in inflows within its first 24 hours of trading, with day-one volume of approximately $15.5 million growing to around $76 million by the following session. Total assets under management reached roughly $170 million within days of launch, a meaningful initial scale even if it sits far below the $6.5 billion that BlackRock’s non-staking Ethereum ETF, ETHA, has accumulated since mid-2024. The gap between the two funds reflects both the head start ETHA enjoys and the natural caution institutional allocators bring to genuinely new product structures.
The fee architecture is structured in two layers. A base management fee of 0.25% per annum applies, though a promotional rate of 0.12% is in effect for the first 12 months or until the fund reaches $2.5 billion in assets, whichever comes first. On top of that, the staking fee split of 82% to investors and 18% to sponsors operates as a second, performance-linked fee layer. Taken together, the structure is competitive, and for investors who understand it, the yield component meaningfully changes the economic case for holding Ethereum through a regulated vehicle rather than just buying spot exposure.
ETHB is not the first staked Ethereum product in the US market. Grayscale and REX-Osprey’s ETH + Staking ETF both preceded it, and Grayscale in particular has been operating in this space for several months. What changes with BlackRock’s entry is the distribution scale and institutional credibility behind the product, the same dynamic that played out when BlackRock’s Bitcoin ETF came to market and rapidly dominated the space even though it wasn’t the first spot BTC fund to launch.
The broader implications for the crypto ETF market may matter even more than the ETHB launch itself. If a staked proof-of-stake asset can be packaged into an ETF that distributes monthly yield, the structural template now exists for other proof-of-stake networks. Solana and Cardano staking ETF filings are already pending in front of the SEC, and while BlackRock has not filed for either, its demonstration that the mechanics work will almost certainly accelerate the review timeline for those products.
Industry-wide, crypto investment products attracted more than $1 billion in weekly inflows in the period surrounding ETHB’s launch, with staked Ethereum ETFs capturing a disproportionate share of that flow. CoinShares data confirmed the figure, reflecting what analysts are describing as a structural shift in how large capital allocators are approaching digital asset exposure. Major asset managers now appear to view yield-generating crypto products as an emerging alternative asset class, comparable to how they think about real estate investment trusts or commodity-linked structured products, rather than purely speculative bets.
Lido’s Kean Gilbert put the directional implication plainly when discussing the institutional staking market earlier this year: “Looking ahead, I expect fully staked exposure to become the reference point for ETH ETFs rather than the exception.” That framing, which seemed premature when it was offered in January, looks considerably more prescient now that BlackRock has validated it with product and capital.
Ethereum itself is trading around $2,188 as of Wednesday, down more than 50% from its 52-week high of $4,831 but up roughly 58% from its cycle low of $1,473 earlier this year. US spot Ethereum ETF assets under management across all products have grown to approximately $14.14 billion this month, up from $13.18 billion a month ago, suggesting that institutional accumulation is continuing steadily even as the price sits well below recent highs. The divergence between falling prices and rising institutional AUM is a feature of this market moment, and BlackRock’s ETHB is now part of the mechanism driving it.
On Saturday, March 14, the Ethereum Foundation confirmed via a post on X that it had finalised the sale of 5,000 ETH to BitMine Immersion Technologies at an average price of $2,042.96 per coin, placing the transaction’s total value at approximately $10.2 million.
The announcement arrived without fanfare, which was somewhat deliberate, because the entire point of conducting the deal over the counter was to avoid the kind of visible sell pressure that an exchange liquidation of the same size would have created in a market already navigating significant macro uncertainty.
BitMine, chaired by Fundstrat’s Tom Lee and publicly traded on the NYSE American under the ticker BMNR, is not a speculative buyer loading up on a volatile asset — it is the largest publicly traded ether treasury company in the world, currently holding approximately 4.534 million ETH as of March 8, a stack worth more than $9.3 billion at recent prices.
The fact that the Ethereum Foundation chose BitMine as its counterparty rather than routing supply through exchanges is the most structurally interesting part of this transaction, because it means the ether did not actually leave the long-term holding universe — it simply moved from one institutional balance sheet to another with a longer time horizon.
The proceeds will fund the Foundation’s core operations, covering protocol research and development, ecosystem growth initiatives, community grant programs, and developer support, consistent with the treasury framework the organisation published in June 2025.
That framework established a target annual spending rate of roughly 15% of treasury holdings, alongside a two-and-a-half-year operating buffer designed to insulate the Foundation from having to sell into unfavourable market conditions out of necessity.
This is the second time the Foundation has used a direct corporate OTC sale to raise operational capital, having previously sold 10,000 ETH to SharpLink Gaming in July 2025 at an average price of $2,572.37 — a considerably higher price point that makes the current transaction’s $2,042.96 clearing price a reflection of where ETH has been trading through the first quarter of 2026.
On-chain data shows the Foundation’s treasury currently holds approximately 169,863 ETH, valued at around $359 million at recent prices, while the broader universe of corporate institutional ETH holdings has grown to exceed 5.16 million coins — a number that illustrates the pace at which ETH is migrating from retail and speculative holders toward longer-term institutional balance sheets.
The analytical question this transaction raises is whether a funding model built on periodic direct sales to corporate buyers represents a structural improvement over the previous approach of liquidating treasury holdings on open markets, and the answer seems to be yes, at least in terms of market impact management.
Private placements reduce slippage, limit visible selling pressure on public exchanges, and allow both parties to negotiate terms without moving prices — advantages that become more meaningful as the Foundation’s operational needs grow alongside the scale of the Ethereum ecosystem it is funding.
Whether the OTC model introduces governance concerns worth monitoring is a separate question, because directing large supply flows toward specific corporate accumulation entities creates concentration dynamics that the broader Ethereum community may want to track more closely over time as the Treasury framework matures.

Bitcoin (BTC) managed to climb back above the $70,000 level on Wednesday, demonstrating resilience in price despite several failed attempts over the past five weeks to surpass the $74,000 resistance mark.
Ongoing geopolitical tensions between the United States and Israel-Iran, combined with disappointing February U.S. labor data, have compounded investor caution, tempering enthusiasm for a sustained bullish move in the near term.
ETF Inflows Show Institutional Interest, But Skepticism Remains
While U.S.-listed Bitcoin exchange-traded funds (ETFs) recorded $414 million in net inflows between Monday and Tuesday, these gains failed to counterbalance $576 million in net outflows seen during the previous Thursday and Friday, highlighting cautious market sentiment.
Analysts note that derivatives markets indicate limited optimism among professional traders, suggesting a substantial rally before the end of March is considered unlikely according to call option pricing.
Derivatives Pricing Highlights Limited Upside Potential
Bitcoin call options on Deribit for March 27, with a $78,000 strike price, traded at $704, implying that whales and market makers assign less than a 17 percent probability of BTC achieving roughly a 12 percent gain from current levels.
Meanwhile, the annualized premium for two-month Bitcoin futures remains below the 4 percent neutral threshold, signaling stagnant demand for leveraged long positions even after a brief four-day rally that briefly retested $74,000.
Macroeconomic Concerns Weigh on Trader Sentiment
Professional traders appear wary of maintaining significant BTC momentum due to global economic uncertainty, with inflationary pressures exacerbated by conflict-driven oil price increases, which some strategists suggest offset fiscal stimulus effects.
Seema Shah, chief global strategist at Principal Asset Management, emphasized that investors are increasingly focused on how geopolitical tensions could influence inflation, underscoring broader economic caution across financial markets.
Institutional Adoption Supports Price Stability
Despite macroeconomic headwinds, investment products linked to Strategy (MSTR US) shares continue to underpin Bitcoin prices, with the company posting record daily trading volumes and enabling additional at-the-market share offerings for spot Bitcoin purchases.
X user “gumsays” highlighted that Strategy’s adoption of variable rate perpetual structures could drive purchases of billions of dollars worth of Bitcoin weekly, suggesting that potential ETF inflows may create sustained institutional demand in the medium term.
Traders are likely to maintain a cautious outlook until after March before anticipating Bitcoin to break the $78,000 threshold, as broader market dynamics and derivatives activity continue to reflect measured sentiment rather than outright enthusiasm.
Investor appetite for Bitcoin investment products strengthened again at the start of the week, ending a brief period of withdrawals that had weighed on cryptocurrency-linked exchange-traded funds.
Data from SoSoValue showed that US spot Bitcoin exchange-traded funds attracted approximately $167 million in net inflows on Monday as the cryptocurrency moved closer to the $70,000 price level.
The inflows followed two consecutive trading sessions dominated by redemptions, during which roughly $577 million exited the funds across Thursday and Friday combined.
Bitcoin itself was trading near $70,015 at the time of reporting, according to CoinGecko data, reflecting modest recovery after recent volatility in the broader digital asset market.
The renewed demand suggested that institutional investors were again allocating capital to the largest cryptocurrency as prices approached a psychologically important threshold.
Altcoin ETFs Continue Facing Pressure
While Bitcoin funds regained momentum, investment vehicles tied to other major cryptocurrencies continued to experience significant selling pressure despite modest price gains in their underlying assets.
Exchange-traded funds linked to Ether, XRP, and Solana all recorded further net outflows on Monday, extending a multi-day trend of investors withdrawing capital from altcoin-focused products.
SoSoValue data indicated that Ether ETFs lost $51 million during the session, while XRP products saw $18 million leave the funds and Solana ETFs recorded withdrawals of roughly $2.5 million.
Across the past three trading days, Ether has experienced the largest cumulative losses among the group, with total outflows reaching approximately $225 million.
Although selling pressure in Ether and Solana funds has gradually moderated over the same period, XRP products have experienced accelerating withdrawals totaling roughly $41 million since Thursday.
Solana-related funds have also seen consistent but smaller outflows, with around $16 million exiting the products during the recent three-day stretch.
Market Sentiment Influenced By Geopolitical Developments
The broader cryptocurrency market received a temporary boost after comments from US President Donald Trump suggested that tensions related to the conflict involving Iran could soon ease.
Trump told reporters on Monday that the war with Iran could be approaching its conclusion, a development that helped calm financial markets and pushed global oil prices lower.
Lower energy prices and reduced geopolitical uncertainty often encourage investors to take on more risk, which can support assets such as cryptocurrencies and technology-linked investments.
During the same period, several major digital tokens recorded gains of between three and five percent over a twenty-four-hour timeframe, according to market data from CoinGecko.
Despite those price increases, the continued withdrawals from altcoin ETFs indicated that institutional investors remained cautious about committing capital beyond Bitcoin itself.
Analysts Warn Market Bottom May Not Be Reached
Some market analysts have warned that it may still be too early to conclude that the recent downturn in the cryptocurrency market has fully run its course.
A CryptoQuant analyst known as IT pointed to the Bitcoin long-term holder to short-term holder spent output profit ratio as an indicator that selling pressure remains present among newer market participants.
The metric recently dropped to 0.89, suggesting that short-term holders were continuing to sell Bitcoin at a loss rather than realizing profits on their positions.
Such behavior is typically associated with periods of market stress, when investors who entered positions during higher price levels decide to exit as volatility increases.
However, the analyst emphasized that the current readings do not yet reflect the type of widespread capitulation historically associated with the formation of a definitive market bottom.
As a result, the data suggests that while pressure in the market is increasing, a clearer turning point for Bitcoin prices may still lie ahead.
If you’ve ever played the slot machines at Las Vegas you’ll understand just how exciting it can be. That dream of landing a massive, million-dollar payout, plus the holidays, the Lamborghini and the luxurious penthouse apartment it’ll buy are all part of the appeal.
But it’s not just the prospect of winning that makes slots so much fun. There’s a real allure to slots in general. They’re action packed, colorful, thrilling and infuriating, no matter if you’re playing at Vegas or online. They exude auditory appeal.
One of the major attractions of slots is their simplicity. They’re so easy to play, there’s virtually no learning curve involved. You simply drop in a coin (or make a deposit online) and hit that “spin” button to see if you’ve won. There’s no rules to master, no complex etiquette to worry about. It’s as easy as can be.
There’s the psychological side to slots, too. Every time you hit that button, you’re venturing into the unknown, and it’s a huge draw for every player. Just like watching a cliffhanger on your favorite TV show, the anticipation creates incredible excitement – will this be the moment you finally land the jackpot? Probably not, but the chance of a payout always exists, and so each time you push that button you’’ll be holding your breath, waiting to see what rewards it will bring.
There’s established science behind this. The human brain feeds on surprises and rewards, and each time you win it generates a massive rush of serotonin, the chemical that makes you feel good. Those moments when you come close are a real motivator too – the symbols line up, you think you’re about to hit four-in-a-row and grab the big money, only for the last one to stop just short. Surely you’ll get it next time? Whether you win or lose, the prospect of a payout arriving soon is always in the back of your mind.
Advances in technology have made slots even more appealing than ever. The clunky, mechanical machines of yesteryear with their massive levers are a thing of the past. These days, slots are entirely computerized, they feature dazzling graphics, gripping storylines and interactive elements that make them more engaging than ever.
With generative AI, players can even design the slots they want to play. Tools such as SlotGPT make it simple for anyone to describe their dream slot machine, including its theme, the characters and so on, then play it for free or with real money online. Players are essentially creating their own slots, making them more personalized and immersive. User-generated experiences are another development that only enhances slot’s appeal.
Technology is impacting slots in other ways too. AI has enabled the creation of machines that learn player’s gaming preferences, while advances in augmented reality and virtual reality make the experience more immersive than ever.
The psychology behind slot machines is fascinating, but it’s even more important to emphasize the need for responsible play. Players have to remember that these machines are designed as a form of entertainment – they’re not designed to make you rich. That’s why players must exercise self-control and, if necessary, take advantage of tools such as deposit limits, time limits and self-exclusion features to ensure they don’t play excessively.
A Bitcoin bottom signal that previously preceded a powerful rally has reemerged, but shifting liquidity dynamics and deteriorating fund flows suggest that any recovery may unfold far differently from the surge witnessed in 2024.
Market observers are closely watching on-chain and macroeconomic indicators, as historical risk models now show conditions resembling those that marked the end of the prior major correction cycle.
On-Chain Metrics Flash Familiar Warning
Data from Swissblock shows Bitcoin has spent 25 consecutive days in its “extreme high risk” zone, surpassing the 23-day stretch recorded in 2023 before prices rebounded sharply.
Historically, such prolonged stays in elevated risk territory have coincided with late-stage drawdowns that eventually transitioned into durable bottoming structures and subsequent bullish expansions.
MN Capital founder Michaël van de Poppe highlighted the BTC versus supply in profit and loss chart, noting that price interaction with these levels has previously marked accumulation phases.
In 2023, the shift from high risk to low risk aligned with the beginning of a rally that ultimately delivered gains exceeding 130% during the following year.
However, traders caution that the current setup lacks the decisive follow-through buying that characterized prior recoveries, leaving the market vulnerable to renewed volatility.
Demand Weakness And ETF Outflows Weigh On Sentiment
RugaResearch reports that 30-day apparent demand continues oscillating between positive and negative readings, indicating that sustained buying conviction has yet to dominate the tape.
Although selling pressure appears to have moderated in recent sessions, analysts argue that inconsistent demand undermines confidence in a near-term breakout.
Exchange-traded fund flows further complicate the outlook, with Bitcoin funds recording negative 90-day rolling averages currently sitting at approximately negative $2.06 billion.
Over the same period, cumulative inflows into gold ETFs have exceeded spot Bitcoin ETF flows, suggesting investors may be favoring traditional hedges amid macroeconomic uncertainty.
This divergence in capital allocation reflects a more cautious environment compared with the liquidity-fueled optimism that underpinned previous rebounds.
Macro Headwinds And Key Price Levels
Inflation data also remains a critical variable, as headline Personal Consumption Expenditures hover near 2.9% year over year while core readings remain closer to 3.0%.
Core services inflation above 3.4% reinforces the perception that the Federal Reserve may maintain restrictive policy longer than risk assets would prefer.
Without clear evidence of easing financial conditions, expectations for aggressive liquidity expansion appear limited, potentially delaying any sustained upward momentum in Bitcoin.
CMCC Crest Managing Partner Willy Woo warned that short-term rallies toward $70,000 or $80,000 could encounter renewed selling pressure because “the broader regime is heavily bearish with both spot and futures liquidity deteriorating”.
Woo identified $45,000 as a pivotal level aligned with the prior bear market structure, while $30,000 and $16,000 represent deeper historical support zones tied to long-term trend preservation.
While bottom signals may be forming, analysts emphasize that major drawdowns outside extraordinary policy interventions have historically required patience before translating into durable recoveries.
Ransomware incidents surged by roughly 50 percent in 2025, as attackers increasingly pivoted toward small and medium-sized enterprises rather than pursuing large, high-profile corporate breaches.
According to blockchain analytics firm Chainalysis, nearly 8,000 leak events were recorded during the year, marking a significant escalation in publicly disclosed attacks compared with 2024.
Despite that surge in activity, total on-chain ransom payments declined to $820 million, representing an eight percent drop from the prior year and highlighting a widening gap between attack volume and realized returns.
Structural Shift In Criminal Economics
Researchers pointed to heightened regulatory scrutiny and enforcement actions targeting laundering infrastructure as key factors constraining attackers’ ability to convert extortion demands into cryptocurrency proceeds.
They also cited a growing refusal among large organizations to pay ransoms, which has reduced the financial incentives associated with headline-grabbing corporate intrusions.
“We’re seeing a structural shift in targeting: fewer large, headline-grabbing intrusions and more volume focused on small and medium enterprises. The assumption is simple — smaller victims pay faster,” eCrime.ch founder Corsin Camichel said in the report, adding:
“However, Chainalysis’ data shows payments trending downward despite an all-time high in public claims. That divergence is important. It suggests attackers are working harder for diminishing returns.”
Cheap Access And AI Tools Fuel Volume
The increase in attempted attacks has been linked to a sharp decline in the average price for victim network access sold on dark web marketplaces, which fell from $1,427 in early 2023 to $439 at the start of 2026.
An influx of inexpensive ransomware strains and automation tools, including artificial intelligence integrations, has lowered barriers to entry and enabled less sophisticated actors to launch campaigns at scale.
“We are seeing industrialized access pipelines, AI-assisted tooling, and a proliferation of infostealer logs that lower the barrier to entry, which has resulted in an oversupply of cheap but operationally constrained inventory that floods the market and depresses pricing.”
Crypto Losses Continue Into 2026
Although ransomware payments moderated in 2025, the broader cryptocurrency ecosystem continues to face elevated security risks entering 2026, with significant losses recorded from exploits and phishing campaigns.
Cybersecurity firm CertiK reported that $370.3 million in crypto assets were stolen in January alone, with phishing scams accounting for $311.3 million of that total.
The evolving threat landscape underscores how cybercriminal operations are adapting rapidly to enforcement pressure, combining lower-cost tooling with diversified tactics in pursuit of sustained illicit revenue streams.